
Bankruptcy Lawyers in Pittsburgh
Filing for bankruptcy in Pittsburgh triggers an immediate federal automatic stay to halt creditor harassment, foreclosure, and sheriff sales. Experienced bankruptcy attorneys help Allegheny County households protect essential assets while restructuring or eliminating eligible debt. Browse our comprehensive directory below to consult verified local practitioners.
McGrath McCall, P.C. - Pittsburgh, PA
Metz Lewis Brodman Must O'Keefe LLC - Pittsburgh, PA
Scully & Scully, PC - Pittsburgh, PA
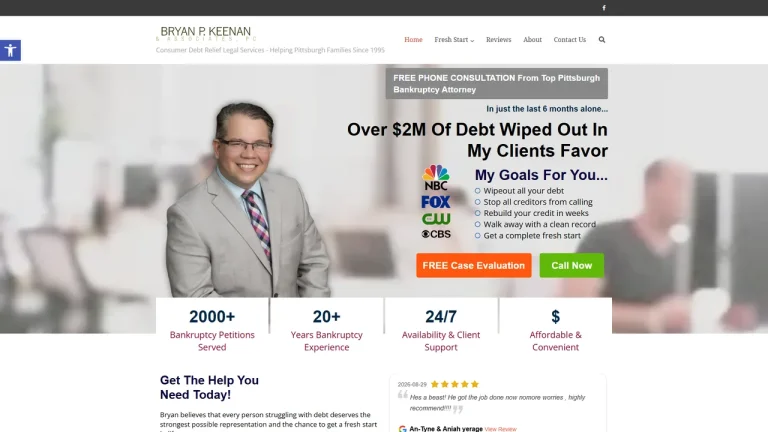
Bryan P. Keenan & Associates, PC - Pittsburgh, PA
Sherrard, German & Kelly, P.C. - Pittsburgh, PA

Buchanan Ingersoll & Rooney PC - Pittsburgh, PA
The Law Office of P. William Bercik - Pittsburgh, PA
Dennis Spyra & Associates - Pittsburgh, PA
Delta Law Group, LLC - Pittsburgh, PA

Law Offices Eric J. Yandrich - Pittsburgh, PA
Frost Law - Pittsburgh, PA
Morella & Associates, A Professional Corporation - Pittsburgh, PA
Saul Ewing LLP - Pittsburgh, PA
Jackson Kelly PLLC - Pittsburgh, PA
Colaizzi Law Group - Pittsburgh, PA
Fiffik Law Group, PC - Pittsburgh, PA
Vorys, Sater, Seymour and Pease LLP - Pittsburgh, PA
Starks Law, PC - Pittsburgh, PA
Leech Tishman Fuscaldo & Lampl - Pittsburgh, PA
Harold Shepley & Associates, LLC - Pittsburgh, PA
J.P. Ward & Associates - Pittsburgh, PA

John M. Silvestri, Esq. - Pittsburgh, PA
Spilman Thomas & Battle, PLLC - Pittsburgh, PA
Federal Bankruptcy Jurisdiction in Pittsburgh and Allegheny County
Consumer and commercial bankruptcy filings in Pittsburgh operate under the exclusive authority of the federal judicial system. All petitions filed by residents and businesses in Allegheny County fall within the jurisdiction of the U.S. Bankruptcy Court for the Western District of Pennsylvania. The court conducts proceedings downtown at the U.S. Steel Tower located at 600 Grant Street, serving as the central venue for hearings, trustee oversight, and formal plan confirmations.
Submitting a bankruptcy petition immediately activates federal statutory protections, halting ongoing litigation in the Allegheny County Court of Common Pleas, freezing bank executions, and stopping scheduled county sheriff property auctions. Creditors are legally prohibited from pursuing garnishments or contacting debtors directly once an official bankruptcy docket number is assigned.
Throughout the greater Pittsburgh metropolitan area-encompassing neighborhoods such as Shadyside, the Strip District, Mount Washington, and surrounding communities in Penn Hills, Bethel Park, and McCandless-individuals facing severe financial strain rely on local counsel. Dedicated Pittsburgh bankruptcy attorneys ensure compliance with Western District Local Bankruptcy Rules and safeguard assets through state or federal statutory exemption schemes.
Typical Bankruptcy Attorney Fees in Pittsburgh
| Case Scenario | Fee Structure | Estimated Cost (USD) | Key Cost Determinants |
|---|---|---|---|
| Chapter 7 Liquidation (Individual / Consumer) | Flat Fee | $1,200 - $2,250 | Means test complexity, asset classification, volume of unsecured creditors |
| Chapter 13 Debt Adjustment (Wage Earner Plan) | District Presumptive Flat Fee / Hybrid | $3,500 - $4,500 | Mortgage arrearage restructuring, vehicle cramdowns, 36-to-60 month plan administration |
| Small Business Restructuring (Subchapter V) | Retainer + Hourly | $6,000 - $16,000 | Commercial lease negotiations, secured vendor claims, cash collateral motions |
| Adversary Proceeding Litigation Defense | Hourly Retainer | $3,500 - $8,500 | Defending non-dischargeability complaints, discovery scope, Western District court hearings |
Critical Legal Deadlines & Statutes in Pennsylvania
Bankruptcy practice requires rigorous adherence to precise statutory timetables. The automatic stay takes effect instantaneously upon electronic filing under 11 U.S. Code § 362, stopping all active collections, including sheriff mortgage foreclosures initiated through the Allegheny County Sheriff's Office. To qualify for Chapter 7 relief, debtors must pass the statutory Means Test established under 11 U.S. Code § 707(b), which examines household gross income across the six full calendar months preceding the petition date against Pennsylvania median benchmarks.
Pennsylvania residents possess the choice to elect either the federal bankruptcy exemptions outlined in 11 U.S. Code § 522(d) or the state exemption scheme provided under 42 Pa. C.S. § 8124. Selecting the optimal exemption structure determines the degree of protection afforded to home equity, retirement savings, and personal belongings. Following petition submission, debtors must attend the Section 341 Meeting of Creditors conducted within 21 to 40 days, and complete an approved financial management course within 60 days following the initial meeting date under Fed. R. Bankr. P. 1007(c). Debtors seeking successive Chapter 7 relief must observe the eight-year waiting requirement codified in 11 U.S. Code § 727(a)(8).
Small Claims Court Judgments vs. Federal Bankruptcy Protection
Magisterial District Courts across Allegheny County adjudicate civil disputes up to $12,000 pursuant to 42 Pa. C.S. § 1515. If an unrepresented consumer allows a debt collector to obtain a default judgment at the local magistrate level, the creditor can record that judgment in the Allegheny County Court of Common Pleas Department of Court Records, establishing an automatic judgment lien against real estate located in the county.
While individual defenses before a Magisterial District Judge only address a single creditor, federal bankruptcy resolves all outstanding liabilities under one comprehensive proceeding. Filing pro se in bankruptcy court exposes debtors to severe procedural vulnerabilities. Unrepresented filers who fail to submit mandatory schedules within fourteen days risk prompt dismissal of their petition, loss of automatic stay protections, and the irreversible liquidation of non-exempt property by court-appointed trustees.
Red Flags When Selecting a Pittsburgh Bankruptcy Lawyer
- Avoid non-lawyer document preparation operations that offer legal forms but are legally barred from representing clients in federal court hearings.
- Be cautious of law firms that fail to provide a customized evaluation comparing Pennsylvania state exemptions against federal bankruptcy exemptions.
- Reject attorneys who quote low initial rates but subsequently add surprise fees for credit report analysis, emergency motions, or trustee meeting representation.
- Steer clear of practitioners who immediately steer every consumer into a Chapter 13 repayment plan without analyzing viability under Chapter 7 liquidation standards.
Frequently Asked Questions
Will filing bankruptcy in Pittsburgh stop an Allegheny County sheriff sale?
Yes. Filing a bankruptcy petition instantly triggers the federal automatic stay, which legally bars the Allegheny County Sheriff from proceeding with any scheduled foreclosure sale of your real estate, provided the petition is filed prior to the completion of the sale.
Can I protect my home and vehicle when filing Chapter 7 in Pennsylvania?
Most filers protect primary assets by utilizing federal bankruptcy exemptions, which provide generous homestead and motor vehicle equity shields. If equity is within statutory boundaries and ongoing payments are current, you can typically keep your home and automobile through reaffirmation agreements.
Where is the Section 341 Meeting of Creditors held for Pittsburgh debtors?
Section 341 meetings for cases originating in Allegheny County are managed under the supervision of the U.S. Trustee Program for the Western District of Pennsylvania. These conferences are routinely conducted via video or telephone conferences, with designated in-person sessions arranged downtown in Pittsburgh when required.
What is the primary difference between Chapter 7 and Chapter 13 in Pittsburgh?
Chapter 7 liquidates eligible unsecured obligations without repayment, concluding within approximately four months for qualifying individuals. Chapter 13 establishes a structured court-supervised repayment plan lasting three to five years, enabling debtors to catch up on delinquent mortgages and keep non-exempt assets.
How does the Means Test evaluate income for Allegheny County households?
The Means Test calculates your average monthly gross earnings across the six calendar months prior to filing and multiplies it by twelve. If your income falls below the median income benchmark for Pennsylvania for an equivalent family size, you qualify to file Chapter 7 liquidation.